DOOH advertising: formats, targeting, costs, and how to buy it

Digital out-of-home advertising is advertising on internet-connected screens in public places: roadside billboards, transit displays, mall and airport panels, screens at the checkout. The screens run off software, so the creative can change by the hour, respond to live data, and be bought through the same platforms as display and video. What follows is the buyer's half of the subject: formats, targeting, price, and platforms. Read it if you're deciding whether DOOH earns a line on the plan.
TL;DR
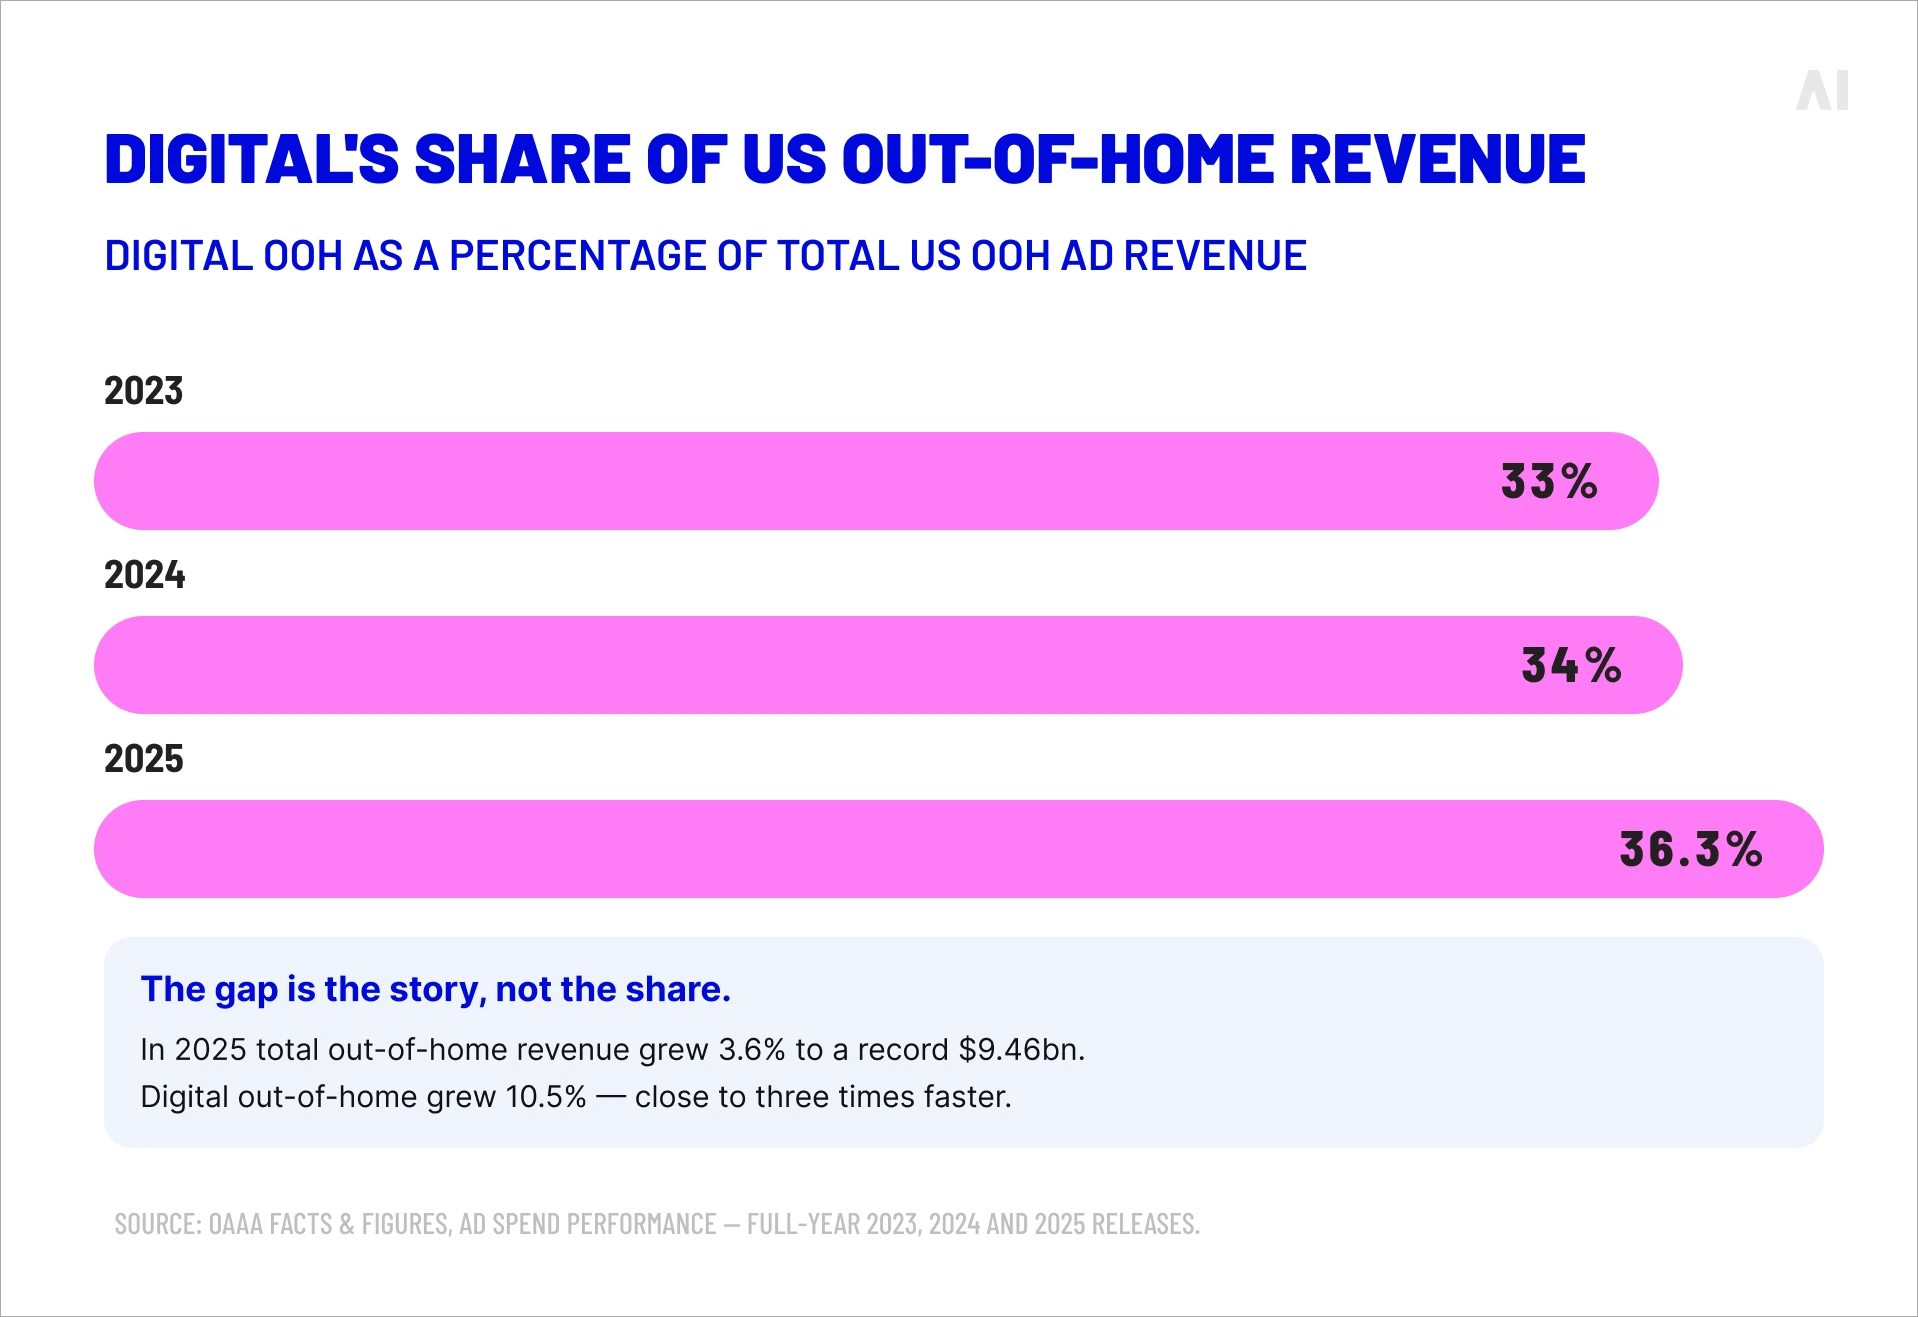
- Digital screens took 36.3% of US out-of-home revenue in 2025, on a record $9.46bn market, with DOOH revenue up 10.5% year over year.
- Programmatic buying is the growth end: US programmatic DOOH is forecast to reach $1.23bn in 2026, though 59% of marketers still buy out-of-home only through direct deals.
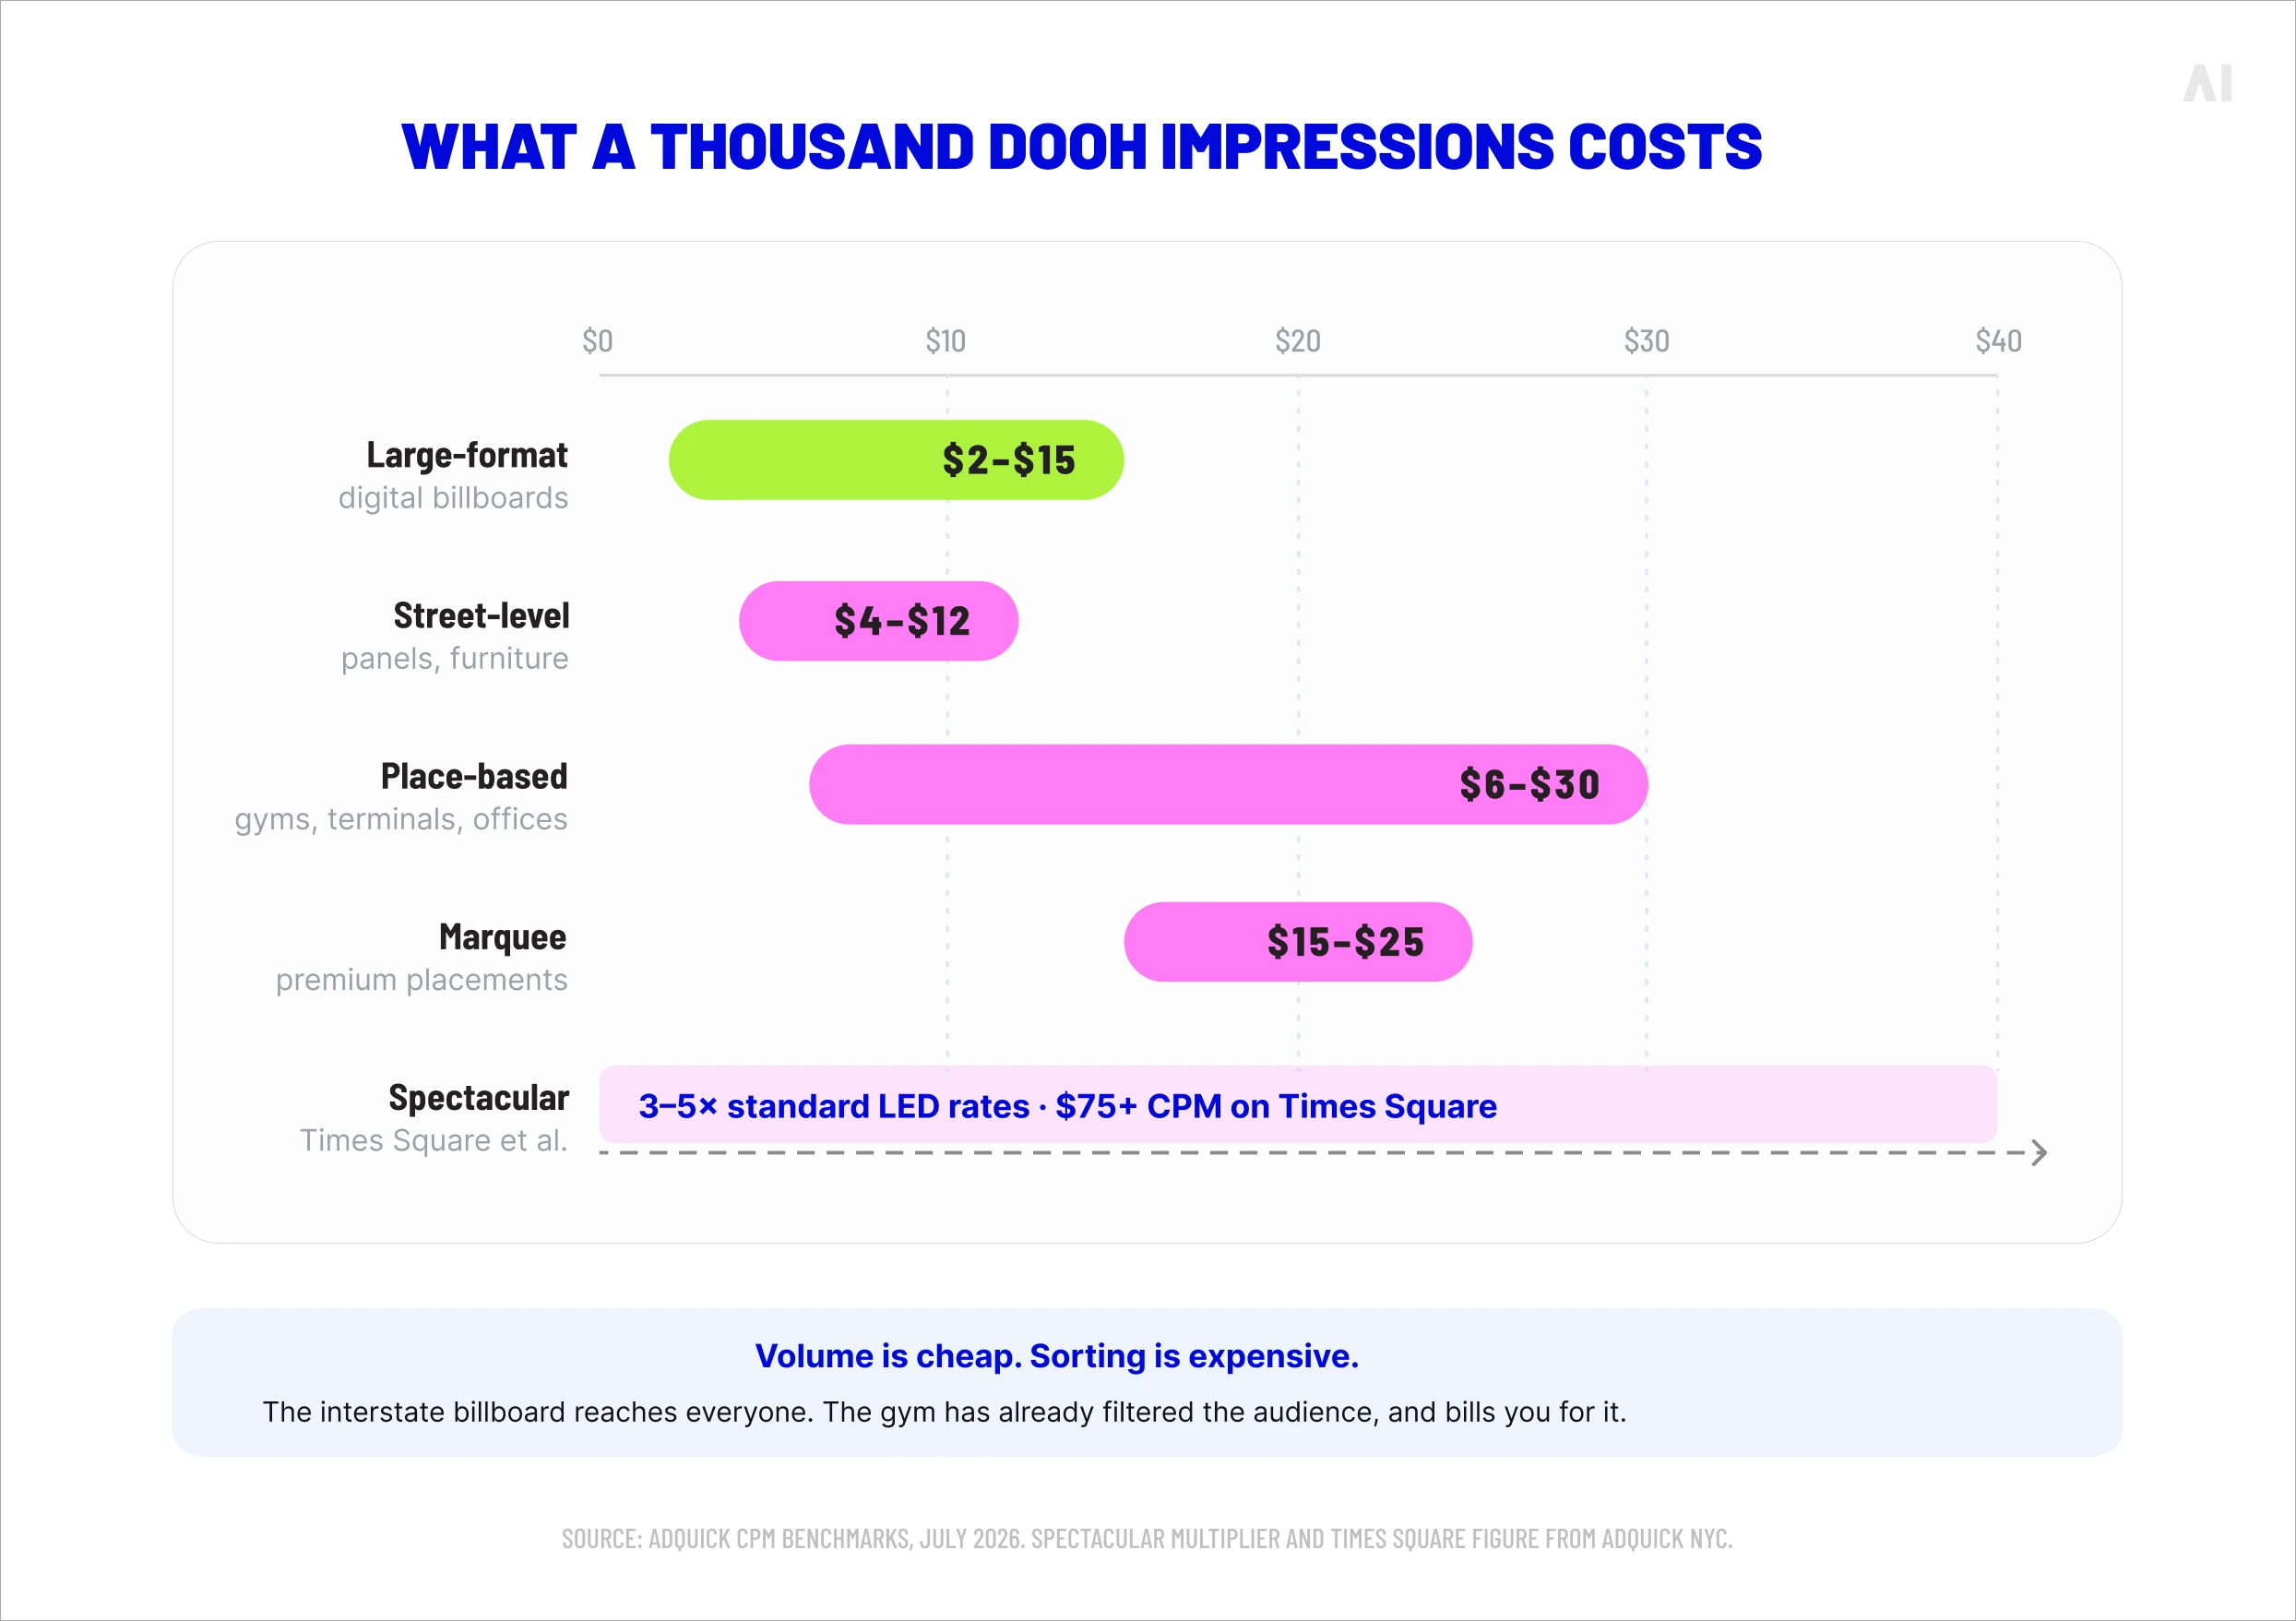
- Entry is cheaper than the format's reputation suggests. A hyper-local street-furniture buy starts around $1,000; CPMs run roughly $2–$15 on digital billboards and $6–$30 on place-based screens.
- You can measure it. Verified plays, audience delivery, foot-traffic lift, and brand lift are all standard. Click-through is not.
Here's how it works, what it costs, and how to buy it.
What is DOOH advertising?
Digital out-of-home (DOOH) advertising delivers ads on digital displays in public and shared spaces. The category covers large-format billboards on highways and building facades, transit screens in stations and shelters, place-based networks inside venues like gyms and airports, interactive kiosks on city streets, and screens at the point of sale.
The difference from a printed poster is that nothing is printed. A DOOH screen is a networked display driven by a content management system. That single fact is what separates the two media, and everything below follows from it. A DOOH ad can:
- carry motion and video rather than a single fixed frame
- change by time of day, weather, live data, or a scheduled trigger
- be aimed at an audience profile rather than a location alone
- be bought programmatically, through a demand-side platform, in hours rather than weeks
- report back on what actually played, where, and to how many people
Out-of-home spent a century selling space: a site, for a month, at a rate. DOOH sells impressions against an audience on inventory that can be changed mid-flight. The screen is still bolted to a building, but the media buy behaves like the rest of a digital plan.
Which is why budgets moved. Digital screens carry the growth in a category that has otherwise been flat for a decade, and they do it inside the buying stack advertisers already run.
💡 For the campaign work: DOOH advertising examples: best practices and creative campaigns that drive results
How DOOH differs from traditional OOH
Traditional out-of-home is a physical product. You buy a site, you print an asset, you ship it, someone pastes it up, and it stays there until the flight ends. If the weather changes, if the product sells out, if the campaign is landing badly, none of it moves.
DOOH removes the print step and everything downstream of it. What remains is a screen, a scheduling system, and a data connection.
The differences compound. Instant changes make dayparting possible, dayparting makes context possible, context makes relevance possible, and relevance is what the recall numbers reward.
For instance, brand-uplift firm Happydemics collated more than 1,300 DOOH campaign studies and found digital inventory prompted brand recall from pedestrians at 2.2× the rate of traditional billboards. Same street, same audience, roughly twice the memory.
None of this makes static obsolete. Long flights on high-frequency commuter routes still do a job that a rotating digital loop does less well, and print carries no share-of-voice risk. But for anything that needs to respond, target, or prove itself, the digital screen is doing work the printed one cannot.
How DOOH advertising works
Behind a digital billboard sits a supply chain that looks more like ad tech than like outdoor. It runs on three layers: the screens and how content reaches them, the data that decides what plays, and the reporting that confirms it played.
The screens and the delivery layer
The physical network is the inventory: billboards, transit shelters, elevator panels, gym screens, checkout displays. Each screen runs a media player, a small computer that takes instructions from a content management system.
The CMS is where the work happens. Advertisers and media owners use it to schedule creative across thousands of displays at once, rotate multiple assets through a loop, and change any of it remotely. A campaign running in forty cities is a scheduling decision rather than forty site visits.
That plumbing is the precondition for everything else. Without remote scheduling there is no dayparting, no weather trigger, and no mid-flight optimization. The screen is just a very expensive poster.
The data and the triggers
This is where DOOH stops broadcasting and starts responding.
Creative can be tied to live inputs: temperature, humidity, time of day, traffic conditions, transit status, sports results, stock levels, air quality, currency rates. A rule is set before the flight—if this, play that—and the platform executes it without anyone touching the campaign.
Screens can also be selected against anonymized mobile movement data, so a buy favors locations that over-index for a target audience rather than locations that are merely busy. A screen with 200,000 weekly passers-by is worth less than one with 60,000 if the 60,000 are the right ones.
Programmatic is the layer that automates the selection. DOOH is integrated directly into the OpenRTB 2.6 specification, which added dedicated DOOH and quantity objects. A DOOH impression is bid on inside the same protocol as a display impression, not through a parallel system built alongside it. That integration is the reason DOOH can sit in an omnichannel plan at all.
Verification and reporting
Reporting covers verified plays, delivered impressions, reach and frequency, and—where a study is commissioned—foot-traffic or brand lift.
What DOOH does not have is a click. Every measurement approach in the medium exists to work around that absence, and they are more sophisticated than the absence suggests.
💡 The full methodology, including how lift studies are structured: (D)OOH metrics explained: how to measure and improve campaign performance
Choosing a DOOH format
Three format families cover most DOOH inventory. They differ less in technology than in what the audience is doing when they pass the screen—and that difference drives creative, targeting, and price.
Large-format is the modern billboard: high-resolution, often full-motion, built to register at distance and speed. It buys presence. Copy has to survive a two-second read from a moving car, which is why the discipline here is subtraction—one idea, one image, a logo you can see from the far lane.
Place-based trades reach for context. A screen in an airport terminal reaches travelers with time and disposable income. A screen above a treadmill reaches someone already thinking about their health. A screen in an office lobby reaches a professional audience at a predictable hour. Dwell time is longer, attention is less contested, and the creative can carry more than a single line.
Point-of-purchase sits closest to the transaction, inside retail media networks and grocery environments, where the gap between exposure and purchase is measured in seconds rather than days. It is the only DOOH format where the ad and the product are within arm's reach of each other.
Formats are not exclusive. Most serious campaigns run large-format for coverage and place-based for relevance, then use frequency capping across both so the same person isn't hit eleven times on the way to work.
One thing surprises buyers arriving from display: the biggest screens are the cheapest per impression. That's next.
Targeting DOOH: dayparting, geotargeting, and POI
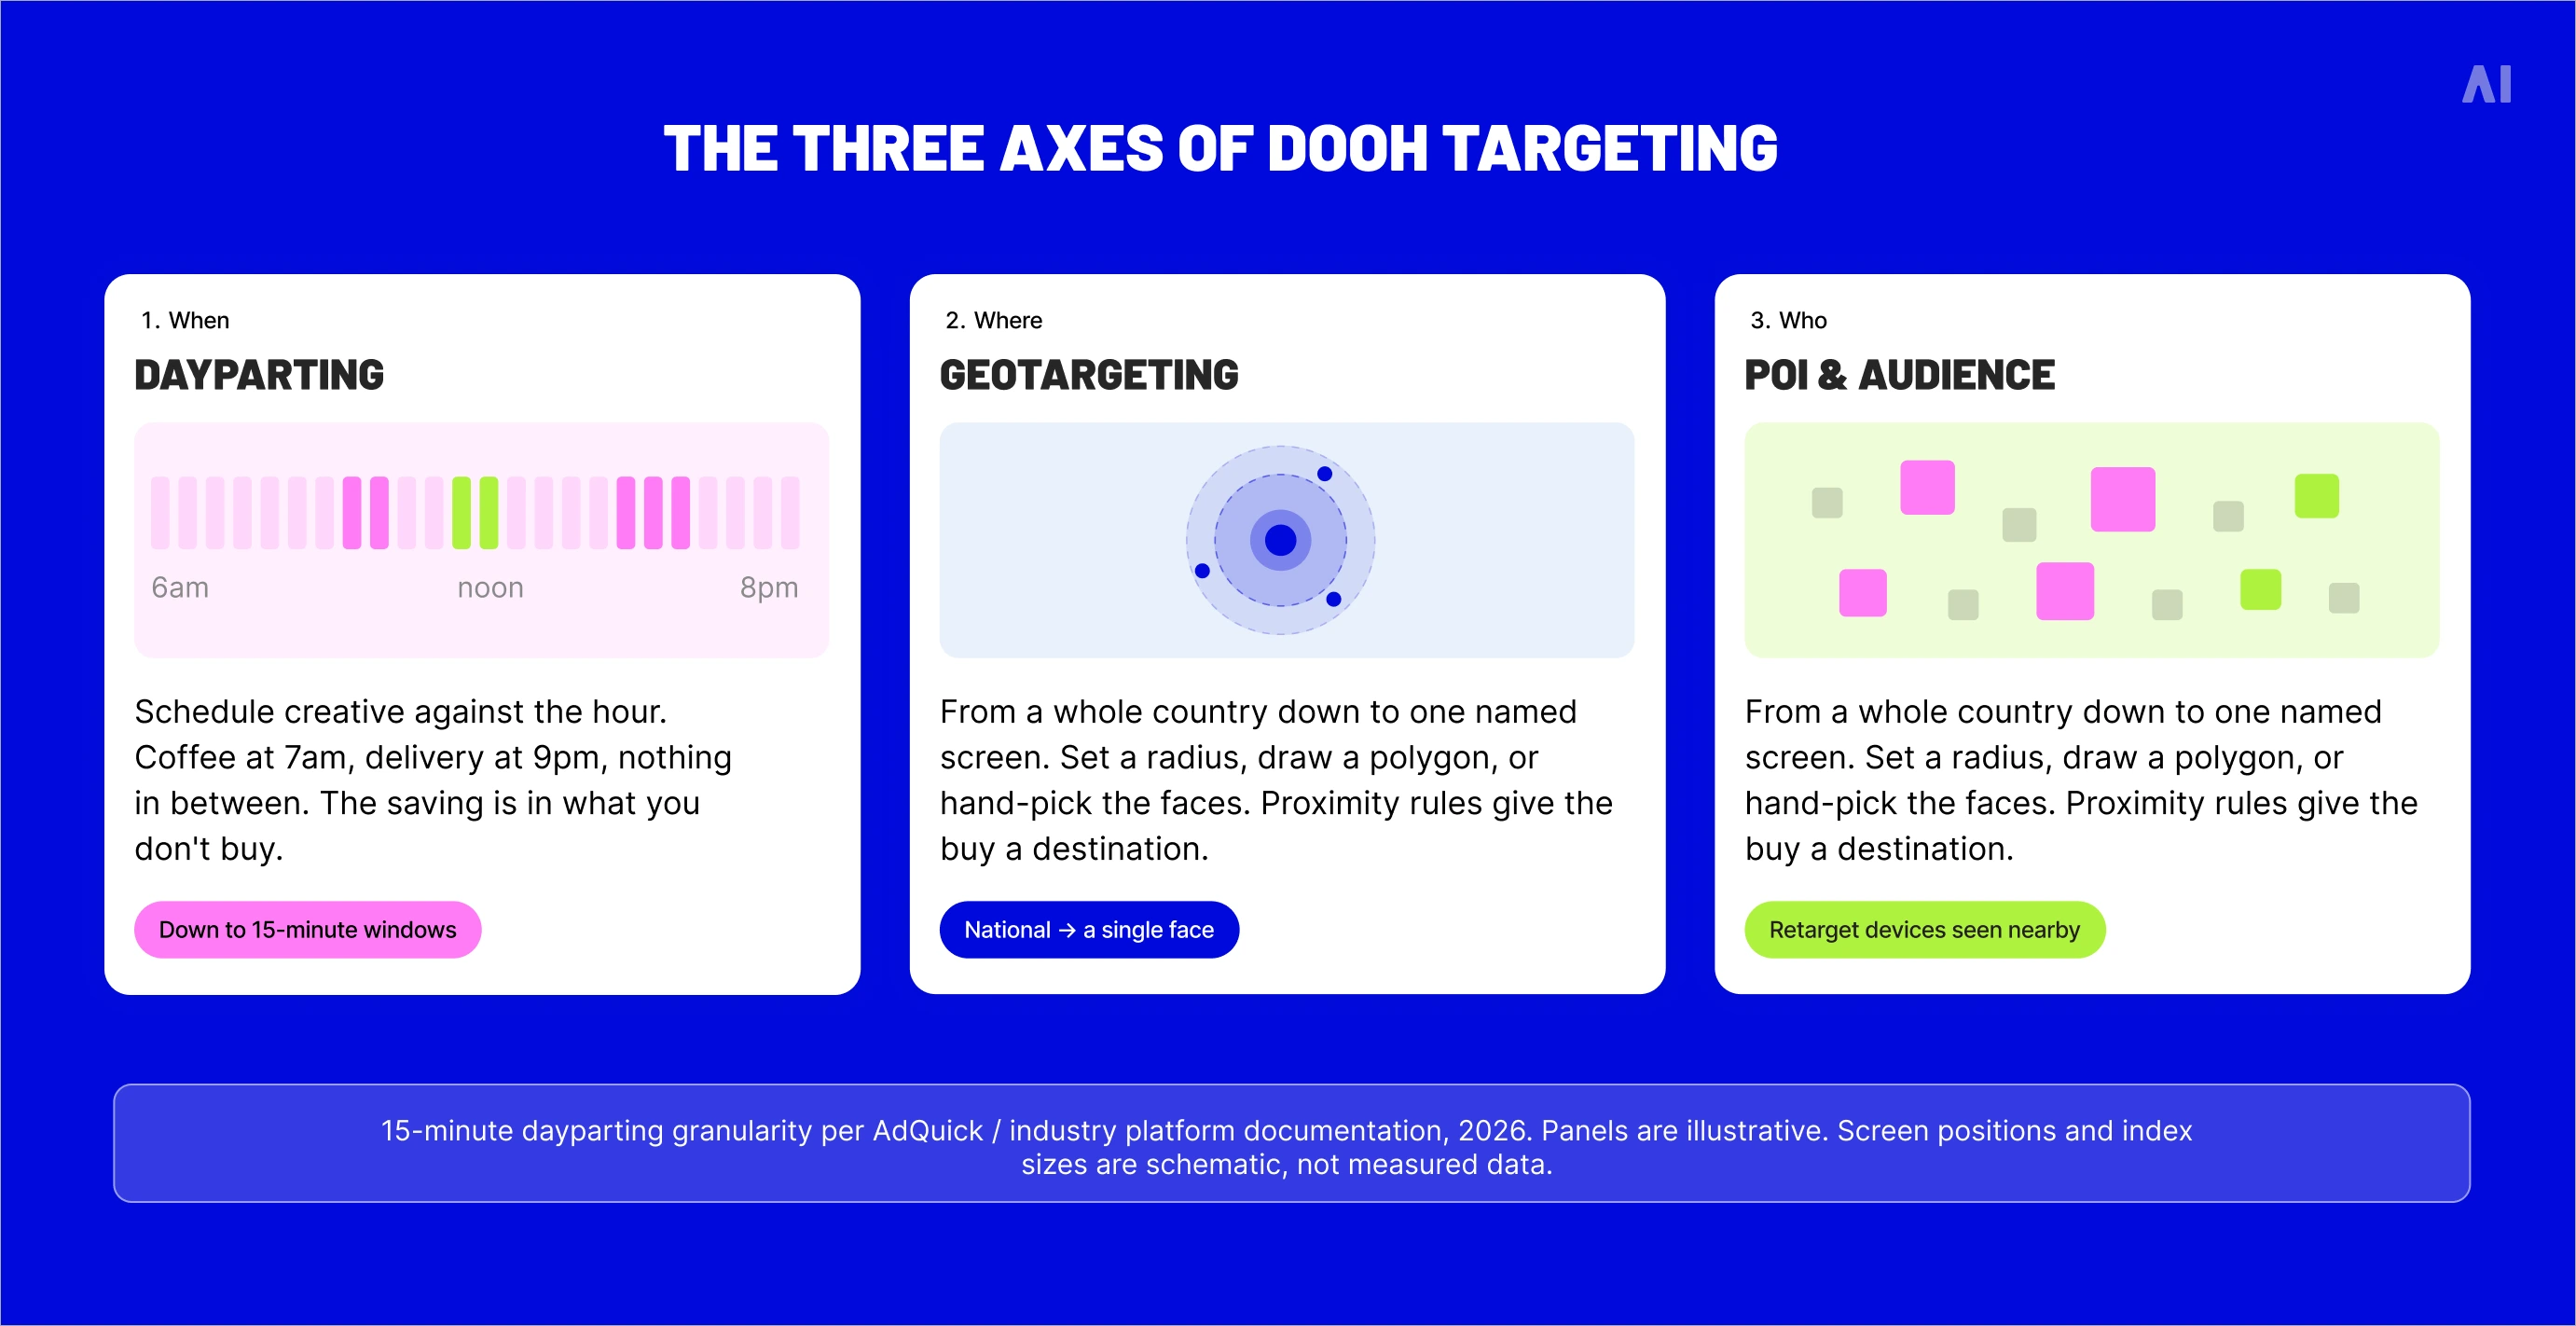
DOOH targeting works on three axes, and most campaigns use all three at once. Together they're the reason a medium once sold by postcode can now be bought by behavior.
Dayparting: buying the hour, not the day
Dayparting schedules creative against time. Coffee at 7am, lunch at noon, ride-hailing at closing time, food delivery at nine.
On programmatic inventory this now goes down to 15-minute windows, which is granular enough to follow a commute rather than a workday. The morning rush at a given station is not a four-hour event; it's forty minutes, and you can buy the forty.
The efficiency gain is in what you don't buy. A ramen brand that only runs at lunch and through the evening commute stops paying for the 6am audience that wants coffee and would not eat noodles at gunpoint. Same budget, fewer wasted plays, higher effective relevance.
Geotargeting: from DMA to a single face
Geographic targeting runs from national down to an individual screen. Buyers set radii, draw custom polygons around catchment areas, or hand-pick named faces.
Proximity targeting is the sharpest version: buying only screens within a set distance of a stockist, a store, or a competitor. It's standard practice in retail and CPG, and it changes what the buy is for. A broad awareness campaign becomes a campaign with a destination, and the destination is measurable.
The constraint is inventory. Tight geographic rules on thin markets produce a plan with nowhere to run, which is where the trade between precision and delivery gets negotiated.
POI and audience targeting: buying behavior, not postcodes
Point-of-interest targeting selects screens by what sits near them and who moves past them. Using anonymized mobile movement data, a buyer can favor screens that over-index for a target segment—screens near universities for a student product, screens on affluent commuter corridors for a premium one.
The same data supports the reverse trip. Devices seen near a screen during a play window can be retargeted on mobile afterward, which is how a billboard acquires a follow-up.
This is the point where DOOH stops being a location buy and becomes an audience buy. Related: location-based advertising: strategy, examples, and what works.
💡 Where AI is taking this: How artificial intelligence transforms programmatic buying in DSPs
Where DOOH advertising performs best
Not all screens are equal. DOOH performs where audience volume meets a reason to look up, and the five environments below deliver that combination reliably enough to plan against.
High-traffic urban centers
Downtown cores, shopping districts, and landmark sites deliver volume and cultural presence at once. The screens are part of the built environment, which means locals stop seeing them as advertising and start seeing them as the street.
The mechanic that makes urban work is dwell. Crosswalks, plazas, queues, and slow traffic all create the pause a moving audience otherwise never gives you. A screen at a light where cars wait ninety seconds is a different product from a screen on a highway at 65mph, even at identical dimensions.
Urban screens work hardest when the creative is local enough to be recognized as local. A national asset dropped into a city center gets the impressions and loses the interest.
Transit and commuter environments
Transit is the fastest-growing out-of-home segment in the US, up 9.2% in 2025 for the second consecutive year, and it earns it.
Commuters are routine, repeat, and often idle. Five minutes on a platform is five minutes with nothing to look at and no way to skip. The same person passes the same screen ten times a week, which builds frequency without the buyer paying for it twice.
Airports concentrate the most valuable version of that audience: travelers with time, money, and a mindset that skews aspirational. It's why premium categories have historically overpaid for terminal inventory and kept doing it.
💡 Deeper on this venue: Digital transit advertising: how DOOH extends reach beyond online media
Retail and point-of-purchase
Screens in and around stores catch people who have already decided to shop. The intent is already there, so the ad can spend its two seconds on the choice rather than the category.
Directional inventory works unusually hard here. Of the consumers who noticed a DOOH ad giving directions to a business, 51% went, and 93% of those bought something (OAAA/Harris Poll, 2024). An ad that tells someone where to go, at the moment they're deciding where to go, converts at a rate no upper-funnel placement will match.
Inside the store, the same logic runs shorter. A screen at the shelf or the checkout has seconds to work with and no journey to interrupt, which is why it suits reminders and promotions rather than brand stories.
Lifestyle and leisure venues
Stadiums, cinemas, gyms, bars, theme parks. Captive audiences, in a good mood, with a demographic profile the venue already knows.
The trade is scale for receptiveness. A concourse screen at a stadium reaches fewer people than a highway bulletin and reaches them while they're happy, which is worth more than the raw numbers imply. Creative that adds to the occasion outperforms creative that interrupts it, and audiences here are unforgiving about the difference.
Measurement in leisure venues tends to be indirect: engagement rates, concession lift, redemption of venue-specific offers. Plan for that before the flight.
Smart-city and civic placements
Kiosks and connected shelters that provide something useful—wayfinding, wifi, transit alerts, air quality—earn attention the surrounding screens have to fight for. People approach them on purpose.
They also carry the data connections that make contextual triggers work at street level. A network that already knows the next train is delayed can serve against that fact in the same second the audience learns it.
The format is young and the inventory is uneven, but the principle holds: a screen people choose to look at beats a screen they walk past.
How much does DOOH advertising cost?
Out-of-home prices on CPM, so most published figures are cost per thousand impressions. Ranges are wide because a roadside panel in a tier-3 market and a Times Square spectacular are not the same product and were never going to price like it.
What a thousand impressions costs
Formats first, and the spread inside each one is as wide as the spread between them.
The counterintuitive part
Large-format screens carry the lowest CPMs in the medium. Place-based screens carry the highest, sometimes triple.
Buyers arriving from display tend to assume the opposite, because the interstate billboard looks like the premium product. What it delivers is scale: enormous impression counts against an audience defined by little beyond direction of travel. Divide the cost by a number that big and the CPM collapses.
The screen above the treadmill charges triple because the network has already done the filtering. Everyone walking past it has opted into a category, and you're paying for that sorting rather than the eyeballs.
Which is what makes the cheap end risky. A large-format plan can look efficient in the spreadsheet and still miss, because a low CPM only helps if the thousand people it buys are people you wanted.
What moves the price
The same screen prices differently depending on four things:
- Market. Top-10 DMAs command a premium; tier-2 and tier-3 markets are materially cheaper for identical formats. In New York, DOOH runs from about $7 CPM on programmatic street-level inventory to $75+ on Times Square spectaculars, across roughly 30,000 digital screens. That's a tenfold spread inside one city.
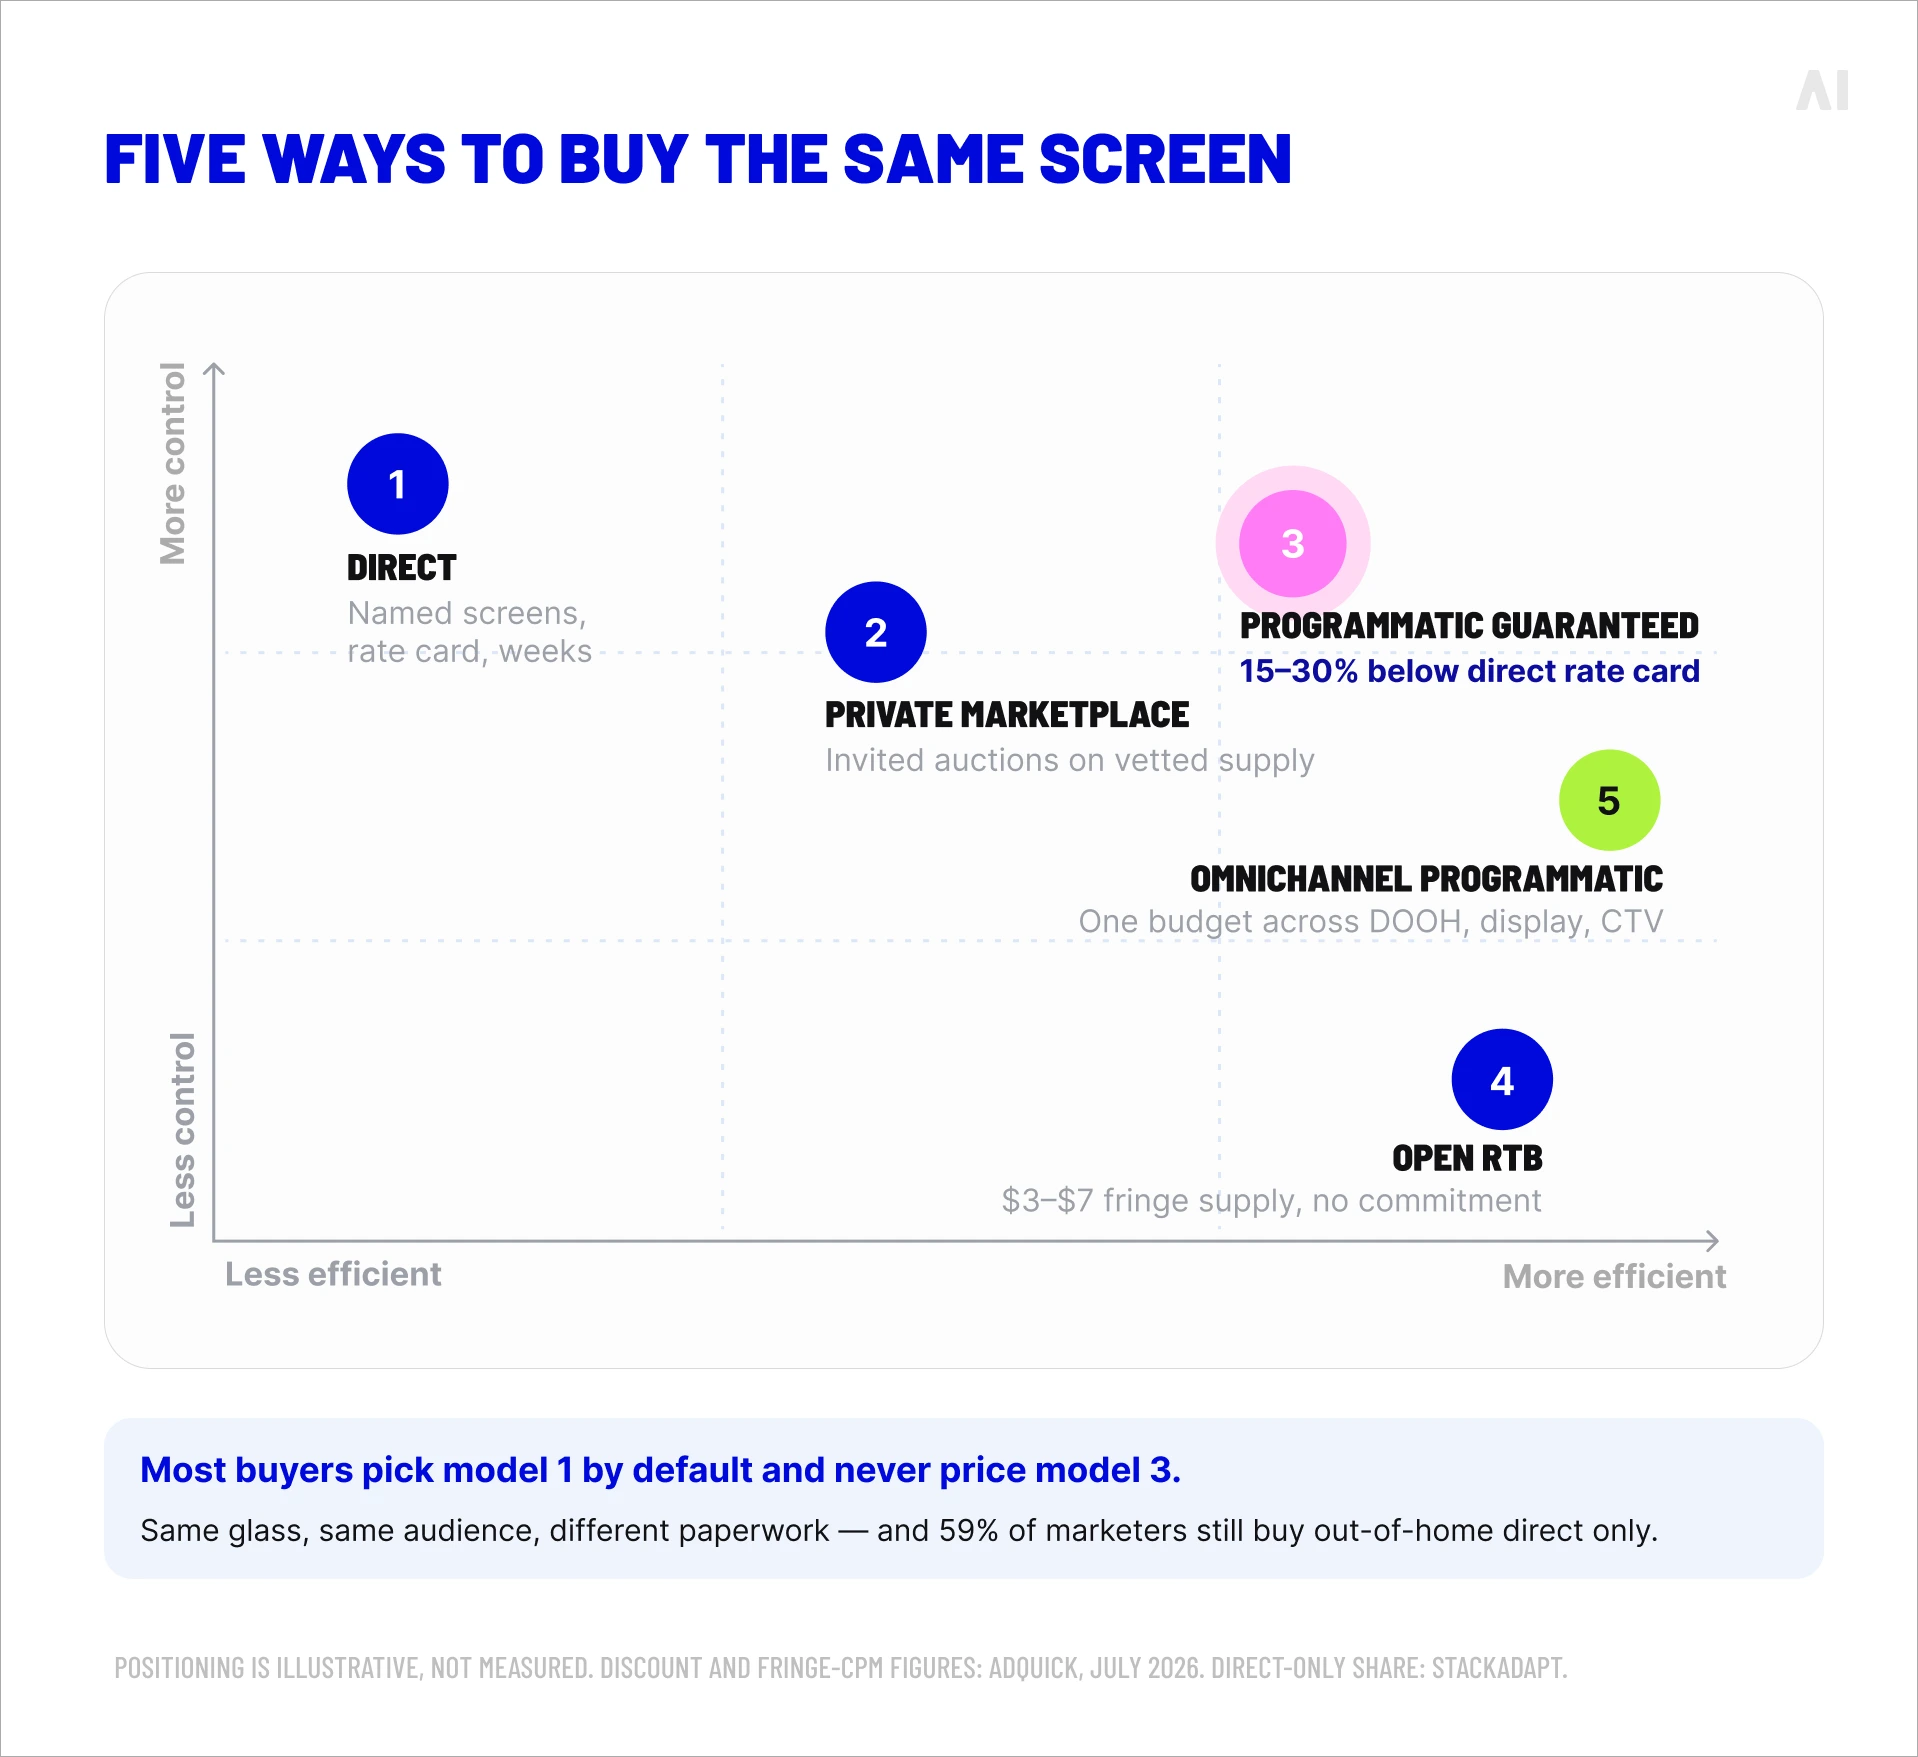
- Buying route. The biggest lever most buyers never pull. Programmatic guaranteed deals on the same physical screen typically run 15–30% below direct rate card, and open-exchange impressions on fringe inventory clear at $3–$7. Same glass, same audience, different paperwork.
- Timing. Peak seasons, holidays, and event windows price up on demand. Longer flights price down on commitment. A two-week burst in December is the most expensive way to buy a screen.
- Format weight. Custom dimensions, audio, and full motion on spectacular inventory carry the 3–5× multiple. You are paying for the production values as much as the position.
What you actually need to spend
Entry is lower than the format's reputation.
- A hyper-local street-furniture buy starts around $1,000.
- National programmatic campaigns run into six and seven figures.
- Premium Times Square inventory can exceed $50,000–$100,000 per month for a single position.
The floor matters more than the ceiling. The reason most brands have never tried out-of-home is a belief that it starts at five figures, and on programmatic it doesn't.
Outcome-based pricing is appearing at the edges. Measured pay-per-play campaigns have reported $0.82 per incremental store visit and $5.75 per incremental online purchase, against typical paid-social CPAs of $15–$40. Treat it as emerging rather than standard, and interrogate the attribution model before you believe the number.
Choosing a DOOH buying model
Five routes to the same screen, at five different balances of control, price, and speed. Choosing between them is the decision that most affects what you pay, and it's usually made by default.
1. Direct buying
Negotiate with the media owner for named screens over a fixed period. You know exactly what you're getting, exactly where, for exactly how long.
Maximum control, maximum certainty, highest price, slowest to move. Lead times run to weeks and the rate card is the rate card.
The right call when a specific site is the point of the campaign—a takeover, a launch moment, a screen your audience already associates with something. If the address is the idea, buy the address.
2. Private marketplace deals
Invitation-only auctions on premium inventory. The media owner selects who gets to bid and on what; buyers get programmatic mechanics on inventory that's been vetted first.
Curated quality with auction efficiency. It's the common landing spot for brands that want programmatic speed without open-exchange uncertainty about where they'll appear.
The trade is that someone else drew the boundaries of what you're bidding on.
3. Programmatic guaranteed
Fixed inventory at a fixed price, transacted through a DSP. The commitment of a direct buy with a programmatic workflow—and, as covered above, typically 15–30% cheaper than the same screen bought direct.
That discount exists because the transaction costs less to execute, not because the inventory is worse. It is the single most reliable saving available in DOOH and most buyers leave it on the table.
💡 Full mechanics: What programmatic guaranteed means for buyers.
4. Open real-time bidding
Live auction, highest bidder takes the play. Maximum flexibility, minimum commitment, least control over exactly where you land.
Good for testing, for trigger-based campaigns where you can't know in advance which screens will qualify, and for short flights—including single-day activations that were impossible before programmatic existed.
The caveat is inventory quality. Open exchange is where the fringe supply lives, which is why it clears at $3–$7.
💡 See what real-time bidding is and why it matters to buyers.
5. Omnichannel programmatic
DOOH planned and bought in the same DSP as display, video, and CTV. One budget, one set of controls, one report.
This is where frequency capping across channels becomes possible, so the person who saw your billboard doesn't get the same message eight more times on their phone. It's where sequencing becomes possible: broad message on the screen, specific call to action on mobile afterward. And it's where budget can move between DOOH and everything else on performance rather than on the annual plan.
Most buyers still don't get here. As mentioned, 59% of marketers buy out-of-home only through direct deals—interest in programmatic is running well ahead of adoption, which is an opportunity for whoever moves first in a given category.
Where to actually buy DOOH: platforms and DSPs
The buying layer consolidated hard across 2025 and 2026, and the map most guides publish is out of date. Here's the current one.
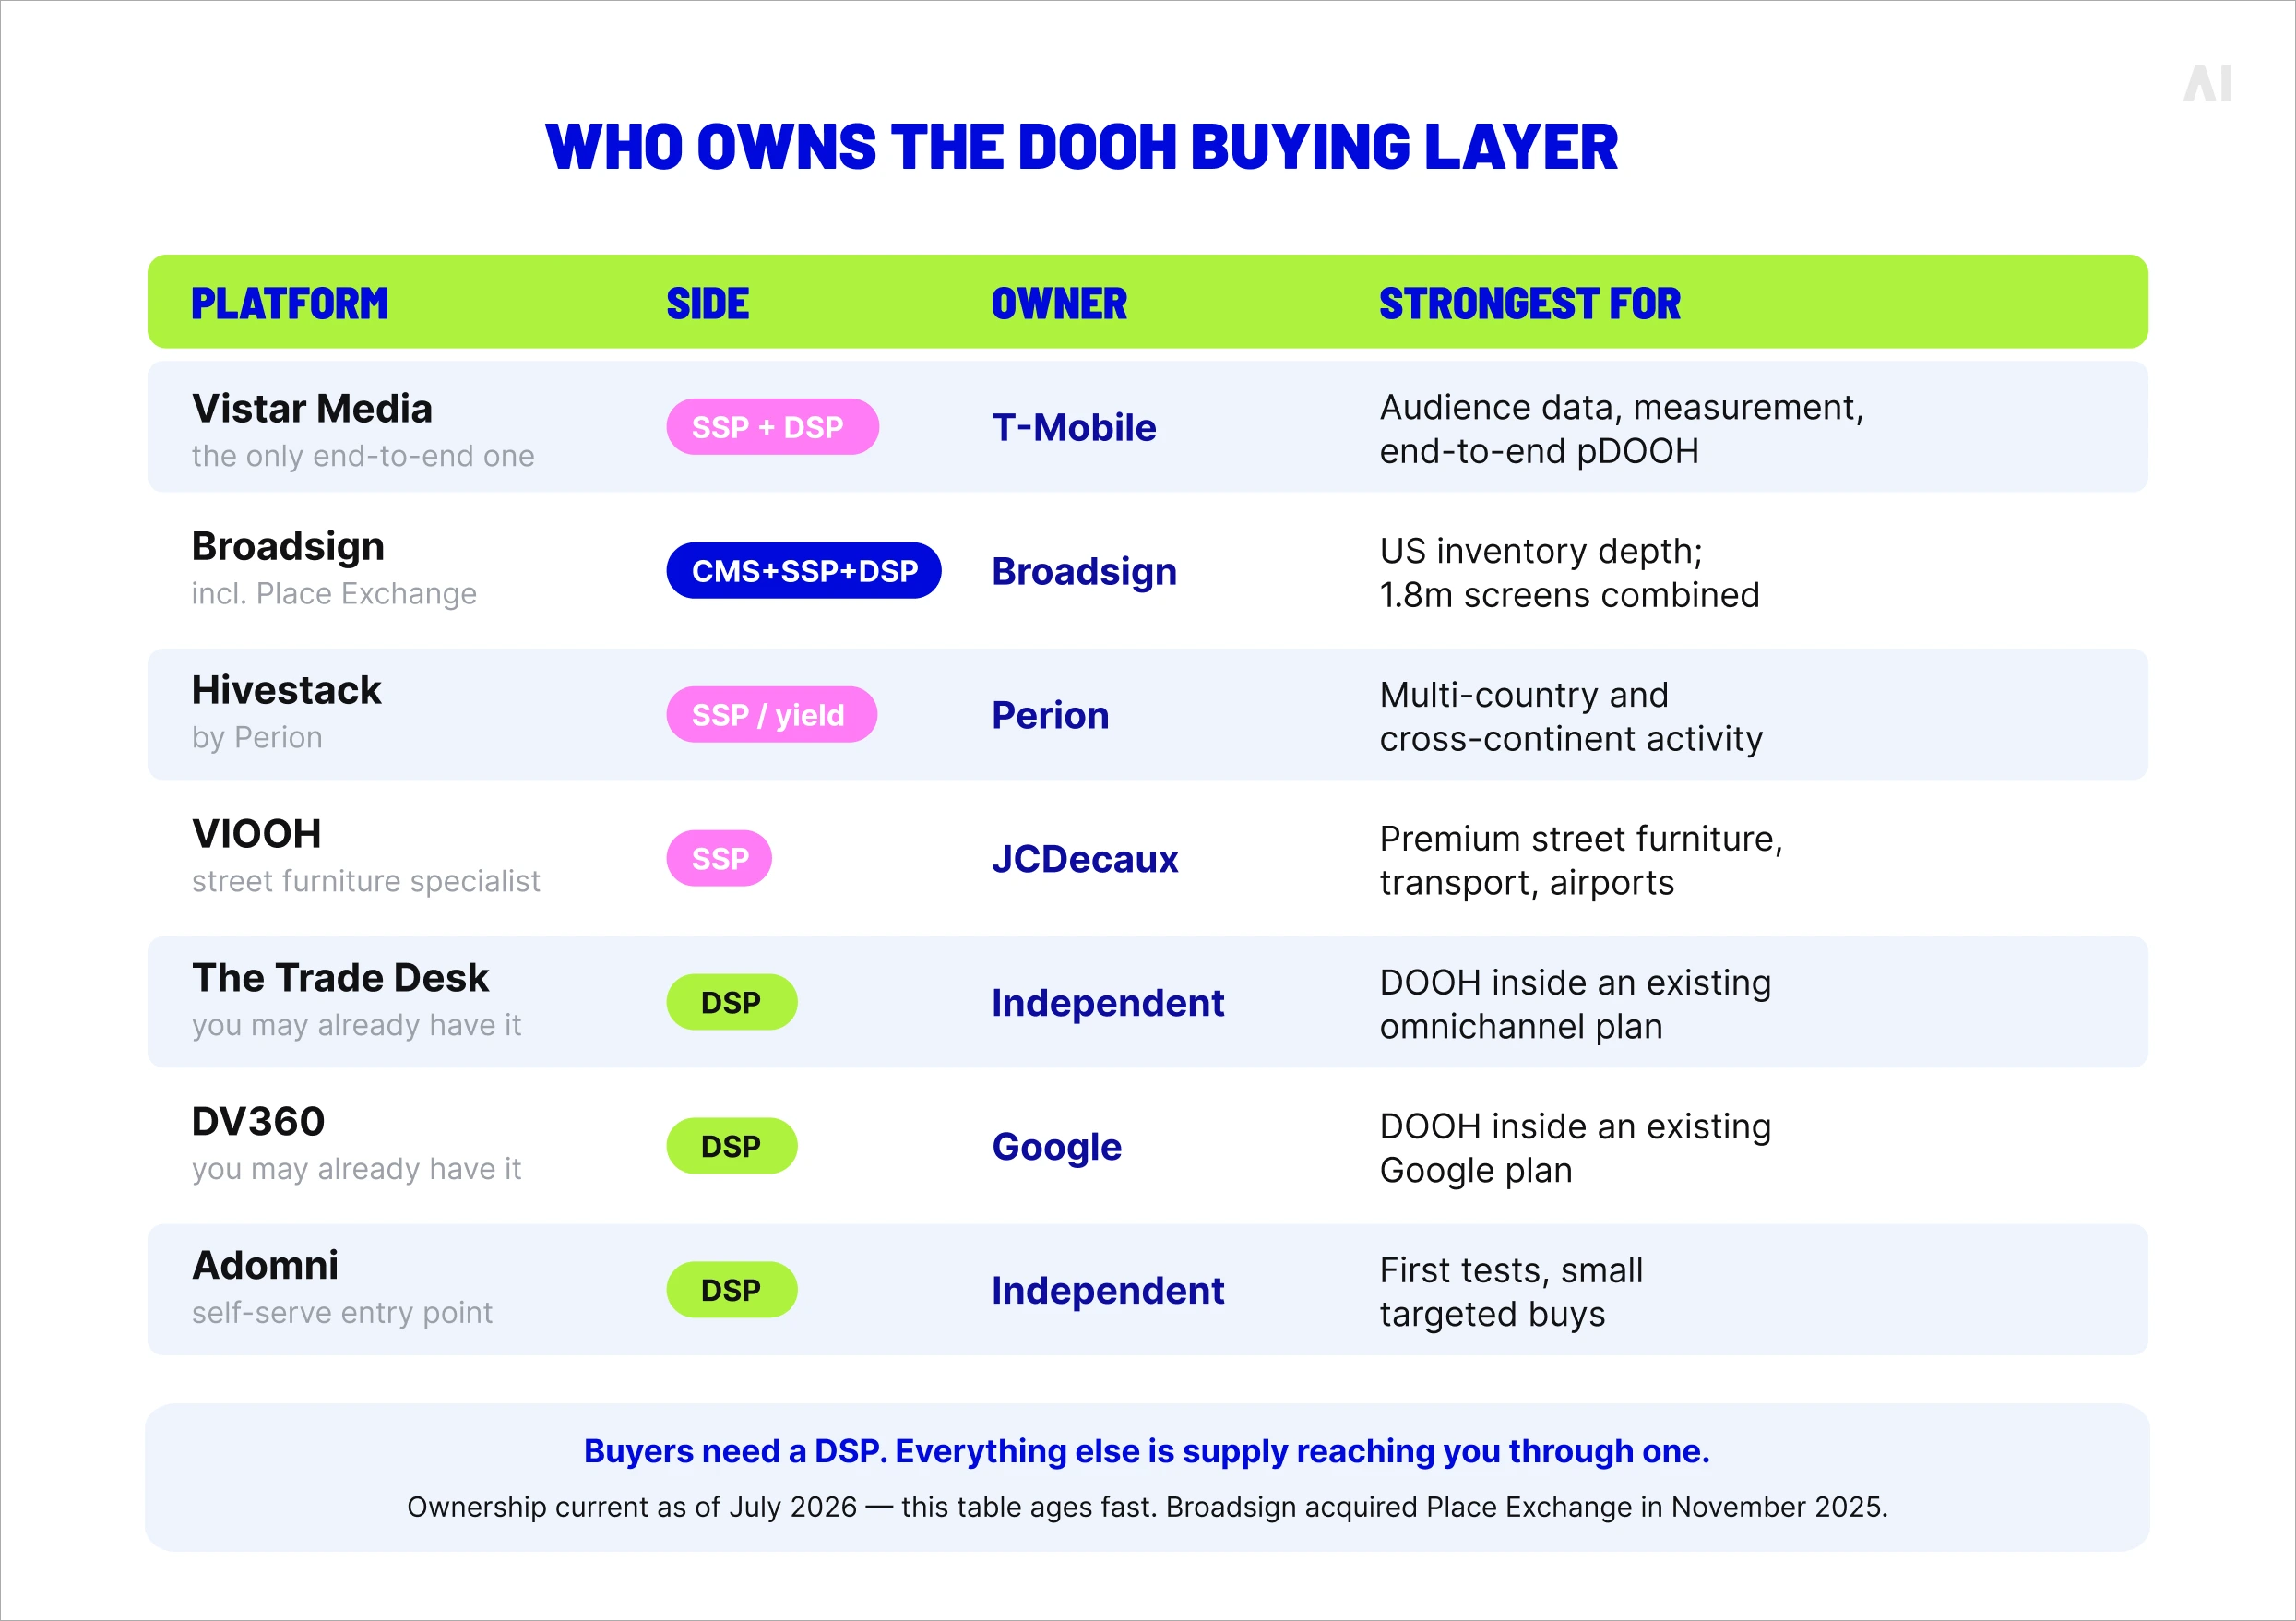
Who owns what, as of July 2026
Three of those changed hands recently. Broadsign acquired Place Exchange in November 2025, creating a combined platform of around 370 staff and 1.8 million programmatically transactable screens. Perion acquired and integrated Hivestack. Vistar Media was acquired by T-Mobile.
The distinction that trips people up
The list above mixes two different things. DSPs are where buyers sit: The Trade Desk, DV360, Adomni, Broadsign Ads. SSPs are where media owners sit: Place Exchange, Hivestack, VIOOH, Broadsign Reach. Vistar runs both, which is why it turns up on every list.
Buyers need a DSP. Everything else is supply reaching you through it.
The practical answer
You probably don't need a new platform.
Vistar and Place Exchange are integrated with both DV360 and The Trade Desk, so a programmatic DOOH deal generally clears through the DSP you already run display and CTV in. For most advertisers, buying DOOH is a supply decision—and the instinct to go shopping for a specialist platform before you've tried the one you own costs time you don't need to spend.
A dedicated DOOH platform earns its place on multi-market activity, on complex trigger logic, or where you need yield-level control. For a first campaign in one country, it's overhead.
Why the consolidation is worth watching
Look at who's holding the pipes now. The largest end-to-end pDOOH ecosystem belongs to a phone carrier. One of the two major North American SSPs sits inside a CMS vendor. The leading global yield layer belongs to an ad tech group.
None of that is a scandal. It's just a structure in which the company recommending inventory often owns some, and will have a coherent story about why theirs fits your brief. The story might even be right. You just can't tell from inside it.
Hence buying supply on its merits.
💡 More on the principle: What walled gardens cost advertisers. On inventory selection specifically: Why DOOH inventory quality, not screen volume, drives campaign performance.
What DOOH delivers
Most guides assert the benefits. Here are the ones with numbers attached.
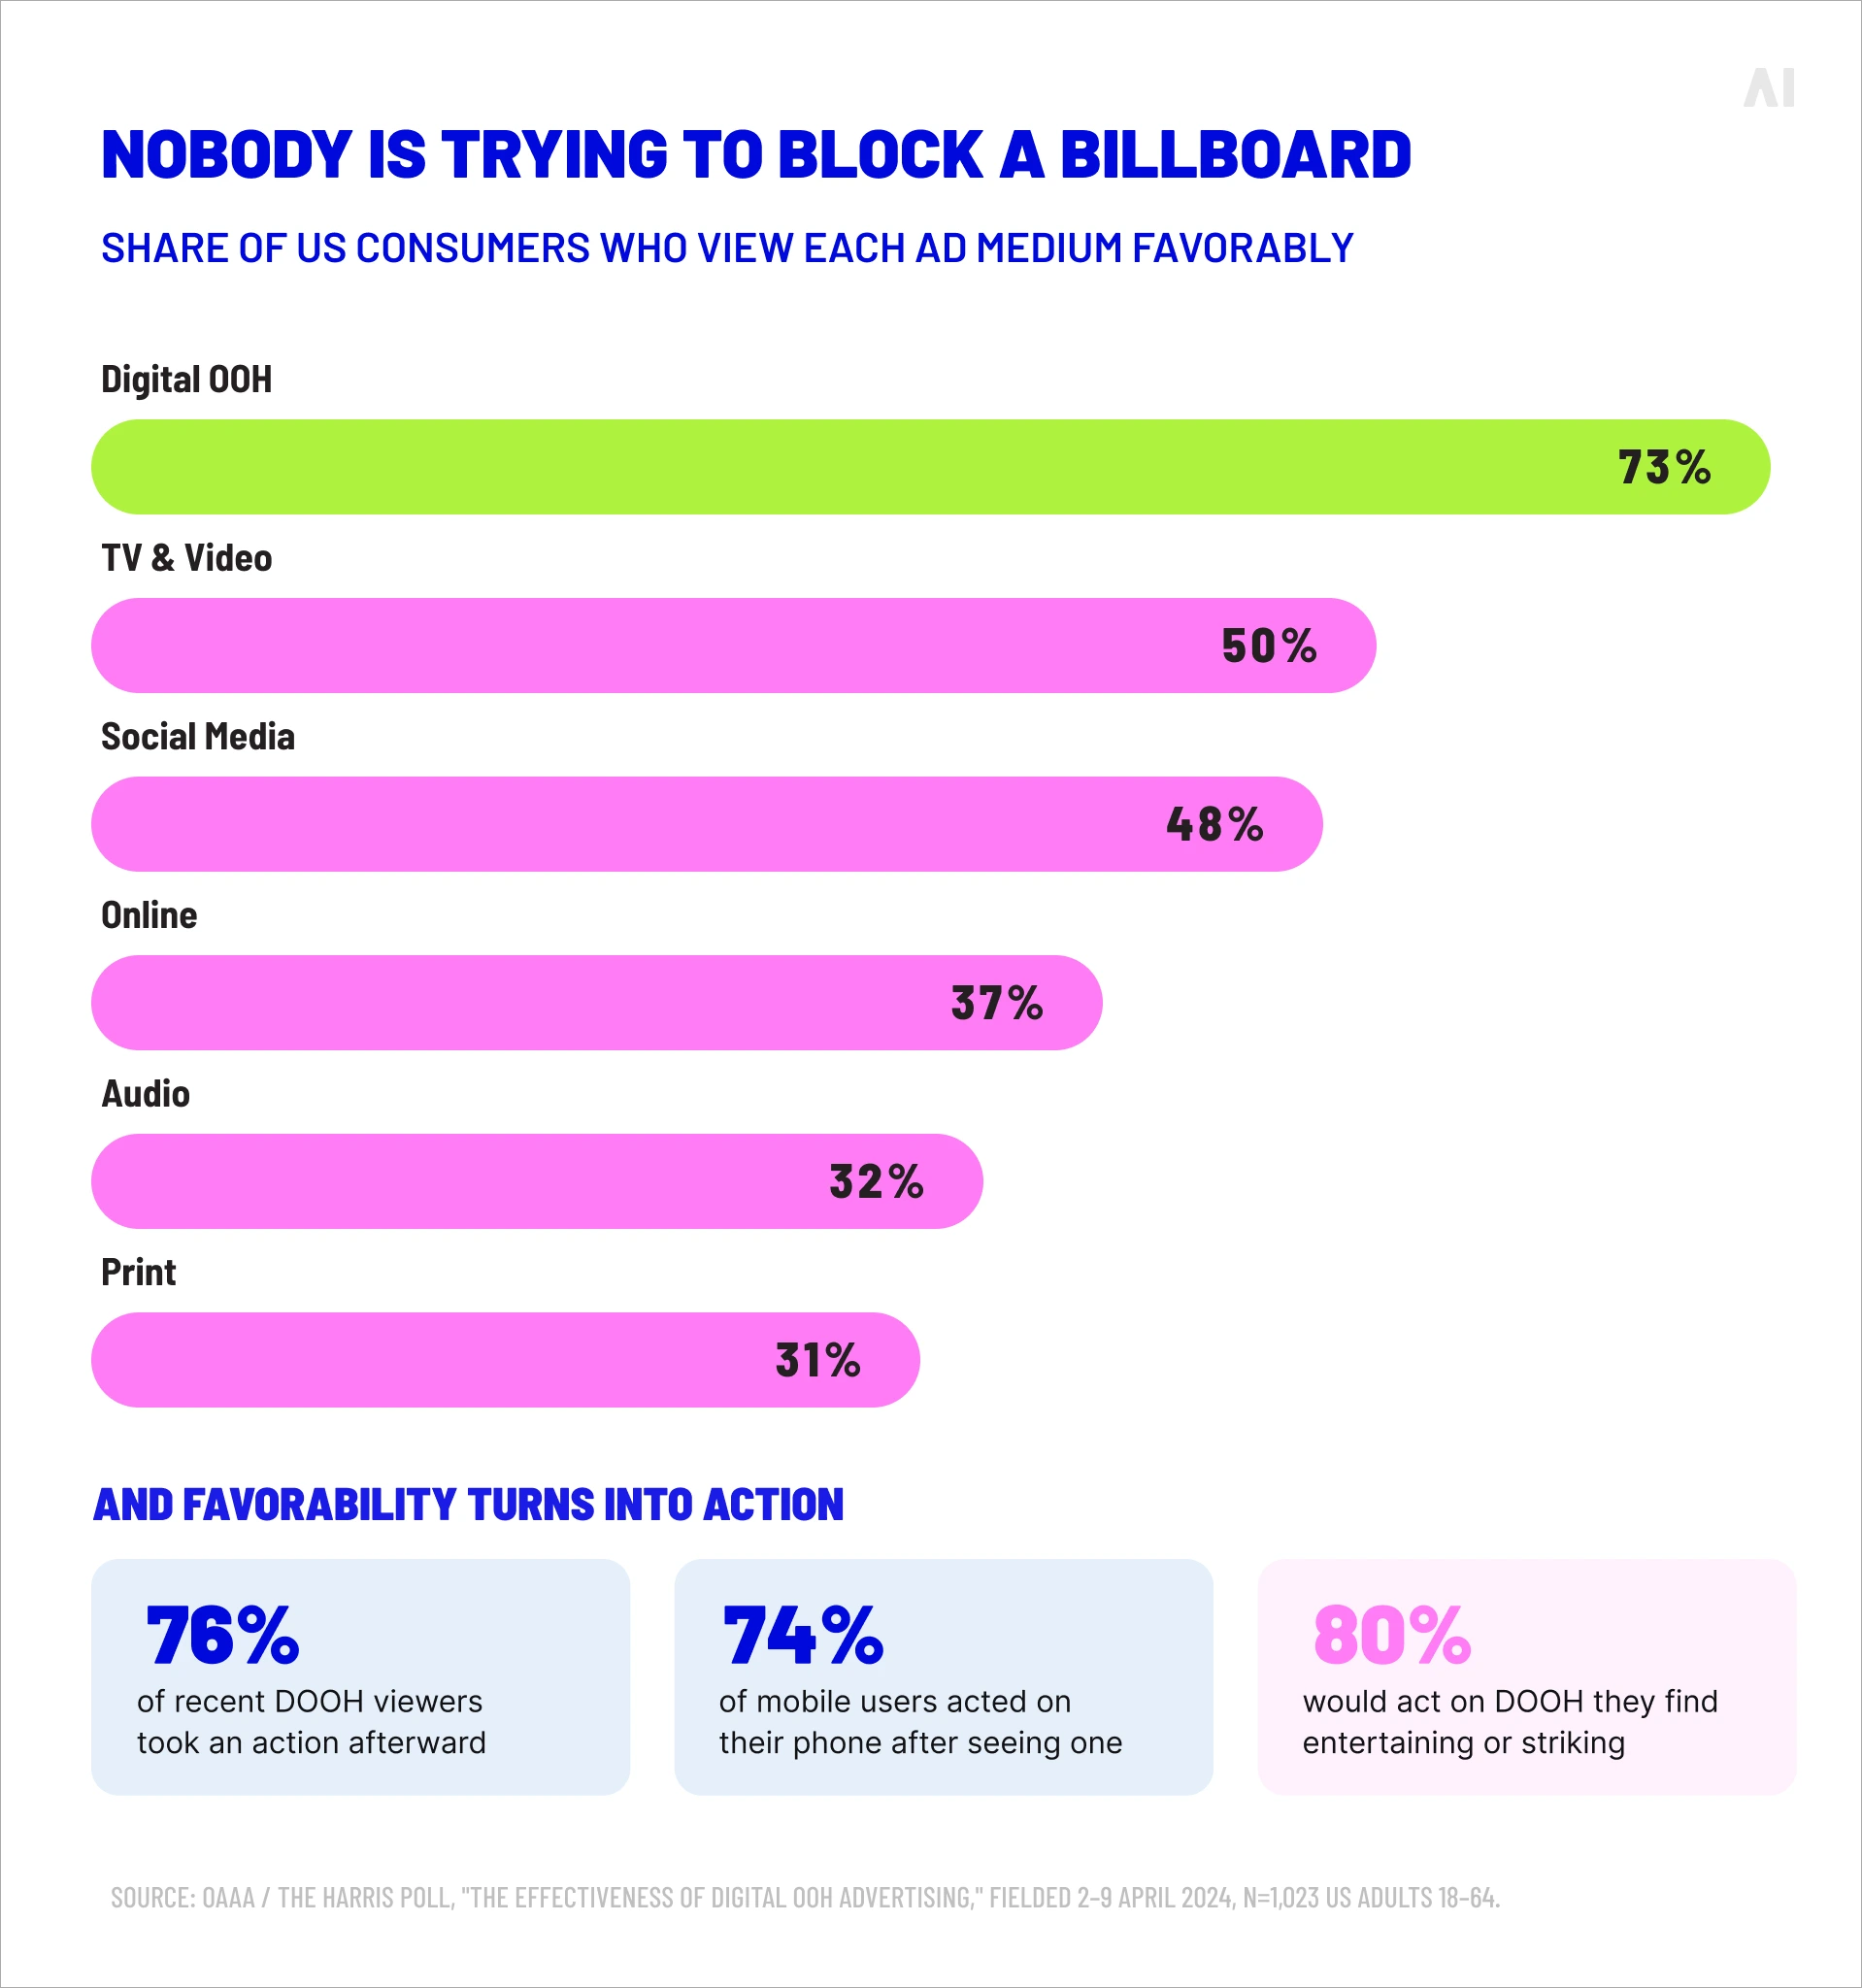
- People don't mind it. 73% of consumers view DOOH ads favorably, against 50% for TV and video, 48% for social, 37% for online, 32% for audio, and 31% for print. It is one of the few remaining formats nobody is trying to block, skip, or install software to avoid. In a category where consent is increasingly the constraint, being welcome is a structural advantage.
- It moves people. 76% of recent DOOH viewers took an action afterward: watching a video (38%), visiting a restaurant (36%), buying in store (30%), telling someone about it (30%), or visiting a store (29%). Creative quality compounds it—80% say they're likely to act on DOOH content they find entertaining or visually striking, which is a larger creative premium than most channels reward.
- It hands off to mobile. 74% of mobile users acted on their phone after seeing a DOOH ad. The screen is the prompt; the phone is the transaction. That's the case for planning DOOH at the top of a sequence alongside connected TV rather than bolting it on afterward as a coverage line.
- It doesn't depend on third-party data. DOOH reaches audiences without cookies or personal identifiers. As data fragmentation and privacy regulation tighten around everything else, a channel whose targeting model was never built on individual tracking gets more useful rather than less. Nobody has to opt in to a billboard.
What changed in DOOH in 2026
The predictions the industry made three years ago mostly landed. AI-driven creative optimization, retail media convergence, privacy-safe measurement—these were the future, and now they're today. Here's what's actually different this year.
Audience measurement is being rebuilt. US audience measurement is moving to a new methodology, with Ipsos selected to deliver it per a March 2026 OAAA release. The pilot launches in the second half of 2026, transition begins in 2027, and full adoption is anticipated in 2028.
If you're planning multi-year DOOH, the currency you measure against is going to move underneath you. Build the comparison points now, while there's still a stable baseline to compare against.
The counting rules are settled, even if the counting isn't. The Media Rating Council's OOH Measurement Standards now define how an out-of-home impression is computed, and MRC accreditation is the audit stamp confirming a provider's methodology has been independently reviewed. Accreditation is product-specific, so check the scope rather than the logo. A vendor accredited for one product is not accredited for its whole line.
Camera-based measurement is on borrowed time. Under GDPR and the EU AI Act, camera-based audience measurement at the screen is hard to defend, particularly where it infers demographic categories from faces. Standards work is converging on methods that count people and measure dwell without producing images at all.
If a vendor is selling you AI cameras in 2026, ask what happens to that product in Europe, and what happens to your historical data when it goes.
Retail media is pulling DOOH inside the store. US retail media spend is forecast at $69.33bn in 2026, and in-store retail media is expected to drive 55.9% of DOOH's total growth between 2025 and 2029.
The fastest-growing DOOH screen is increasingly one you walk past with a basket in your hand. That reclassifies a chunk of out-of-home as a commerce channel, with the closed-loop measurement and the retailer politics that come with it.
💡 Related: Retail media networks: what they are and how they work | AI in digital marketing
What still holds DOOH back
Four problems the category hasn't solved yet:
- Proof of play is not standardized. There is no cross-industry technical standard for verifying that an ad actually played. It remains defined per media owner, in the contract, with self-verification still a large part of the ecosystem. Ask what proof looks like before you sign. "We'll send a report" is not an answer; ask who generates it and whether anyone audits them.
- Fragmentation persists despite consolidation. Fewer platforms has not meant unified methodologies. Comparing delivery across two SSPs still means comparing two definitions of an impression, and the M&A of the last eighteen months has consolidated ownership without harmonizing the maths underneath.
- Privacy pressure keeps tightening. The targeting and attribution that make DOOH accountable both lean on mobile location data. The regulatory direction is one-way, and the medium's best answer—that it doesn't need identifiers to deliver an ad—is only half true once you want to prove the ad worked.
- Upper-funnel attribution is still hard. Footfall attribution and brand lift close part of the loop. Neither settles what a brand-building impression is worth, and performance-led marketers will keep asking a question the medium can only partly answer.
None of these are reasons to stay out. They're reasons to write the measurement plan before the media plan.
Conclusion: building DOOH into a media plan
Start with the objective. Decide whether you're buying reach, context, or proximity to a purchase, because those three answers point at three different formats at three different CPMs—and picking the format first is how campaigns end up efficient at reaching the wrong people.
Then decide how you're buying before you decide what. The gap between a direct rate card and a programmatic guaranteed deal on the same screen is 15–30%. The gap between a siloed DOOH line and a DOOH line planned inside your omnichannel budget is larger still, because that's where frequency, sequencing, and reallocation start working for you.
And demand the measurement plan up front. Foot-traffic lift, brand lift, and verified delivery all have to be specified before the flight runs. Requested afterward, they're an argument.
Which is a fair thing to turn back on us, two paragraphs after a section about platforms with an interest in where your budget lands. So:
- Smart Supply owns no inventory and sells no media. It selects and optimizes supply across 9+ SSPs against your KPIs, it's DSP-agnostic, it's free, and deal IDs come back inside 24 hours.
- That's the Open Garden framework in practice—transparency, customization, efficiency, across 15+ DSPs.
- Elevate doesn't bid or serve ads either. It's a marketing intelligence platform sitting across 12+ DSPs, covering planning, mix modeling, path to conversion, and brand study.
Get in touch to talk through a DOOH plan.